486,532 deliveries in Q3, up roughly 24,000 above the 461,974 consensus Tesla compiled from 24 analysts. Wall Street still expects revenue to come in flat and earnings per share to drop 10% from a year ago. Volume is not the problem. Margin is. Tesla reports after the close on October 21, with the call at 5:30 p.m. ET, and the hinge number sits a few lines below the top of the P&L.
Key takeaways
- Tesla beat Q3 delivery consensus by ~24,000 units, yet revenue is still expected to land flat at $27.8–27.9B.
- Auto gross margin ex-credits is the hinge number, a sequential drop from Q2's already-compressed level would be damaging.
- Regulatory credits collapsed from $439M a year ago to $146M, a line that used to quietly flatter margins.
- Canadian Tesla market share fell from ~45% in 2023 to ~32% by early 2026, and depreciation curves confirm buyers have repriced the brand.
- At 300x expected 2027 EPS of $1.18, the stock is pricing Cybercab and FSD commercialization, not the Q3 car business.
The Delivery Beat That Won't Save the Margin
A 24,000-unit beat on deliveries that produces flat revenue is a sentence that only makes sense if the average selling price has moved down. It has. Revenue grew on deliveries, while average selling price and regulatory credits fell and AI spending and stock-based compensation rose. Regulatory credits were $146 million versus $439 million a year earlier, a line that used to flatter the auto margin and now barely registers.
Consensus expects EPS near $0.43–$0.45 and revenue near $27.8–$27.9 billion, which is the arithmetic of a company selling more cars for less money. The number to watch tomorrow is auto gross margin ex-credits. After excluding about $230 million of one-off items, auto margin was roughly flat sequentially in the prior quarter. Flat is the floor Wall Street is pricing. A sequential step down and the story writes itself.
Energy storage is the quiet second variable. The open question is whether energy margins recover from Q2's sharp drop, or whether further compression is likely as ASPs fall and competition rises. Tesla has leaned on this segment to carry non-auto growth; a second disappointing quarter here lands harder than the headline EPS miss.
Gear worth having
As an Amazon Associate, ThinkEV earns a small commission from qualifying purchases — at no extra cost to you.

WeatherTech FloorLiner for Tesla Model 3
Deep-channel liners that trap every drop of slush and salt. The difference between a ruined interior and a showroom-fresh cabin after a Canadian winter.
As an Amazon Associate, ThinkEV earns from qualifying purchases — at no extra cost to you.
The brand's position in a market Tesla used to own is already visible in the residuals. Canadian Tesla share dropped from roughly 45% in 2023 to about 32% by early 2026, and the depreciation curves tell the same story, the 2023 Model 3 is losing 43% of its value in three years. Buyers have repriced the brand. The margin line is where that repricing finally arrives.
Gear worth having
As an Amazon Associate, ThinkEV earns a small commission from qualifying purchases — at no extra cost to you.

USB-A to USB-C CarPlay Adapter (3-Pack)
Older car USB port, newer USB-C cable: this tiny bridge makes wired CarPlay just work. Three so you never lose the one.
As an Amazon Associate, ThinkEV earns from qualifying purchases — at no extra cost to you.
October 21 Is the First Real Read on the Autonomy Bet
On expected 2027 EPS of $1.18, the multiple is about 300x, and about 13x expected 2026 sales of $106.9 billion. The price rests not on current earnings but on the option value of autonomy and robotics. That is a clinical way of saying the current car business is not what the stock is paying for.
Which means the EPS print is the warm-up. The real event is whatever Musk says about Cybercab timing, FSD revenue recognition, and the robotaxi rollout, the parts of the business that justify the multiple. The three-way autonomy comparison between Waymo, Tesla FSD, and Cruise is the frame; tomorrow's call is where Tesla has to show the commercialization slope is actually a slope.
The macro is not helping. US EV sales were down 4% year-over-year as of March, and Tesla specifically was down 9% in the same window. A delivery beat into a soft market is a share-recapture story, which is useful. It is not a margin story, which is what the multiple needs.
Gear worth having
As an Amazon Associate, ThinkEV earns a small commission from qualifying purchases — at no extra cost to you.
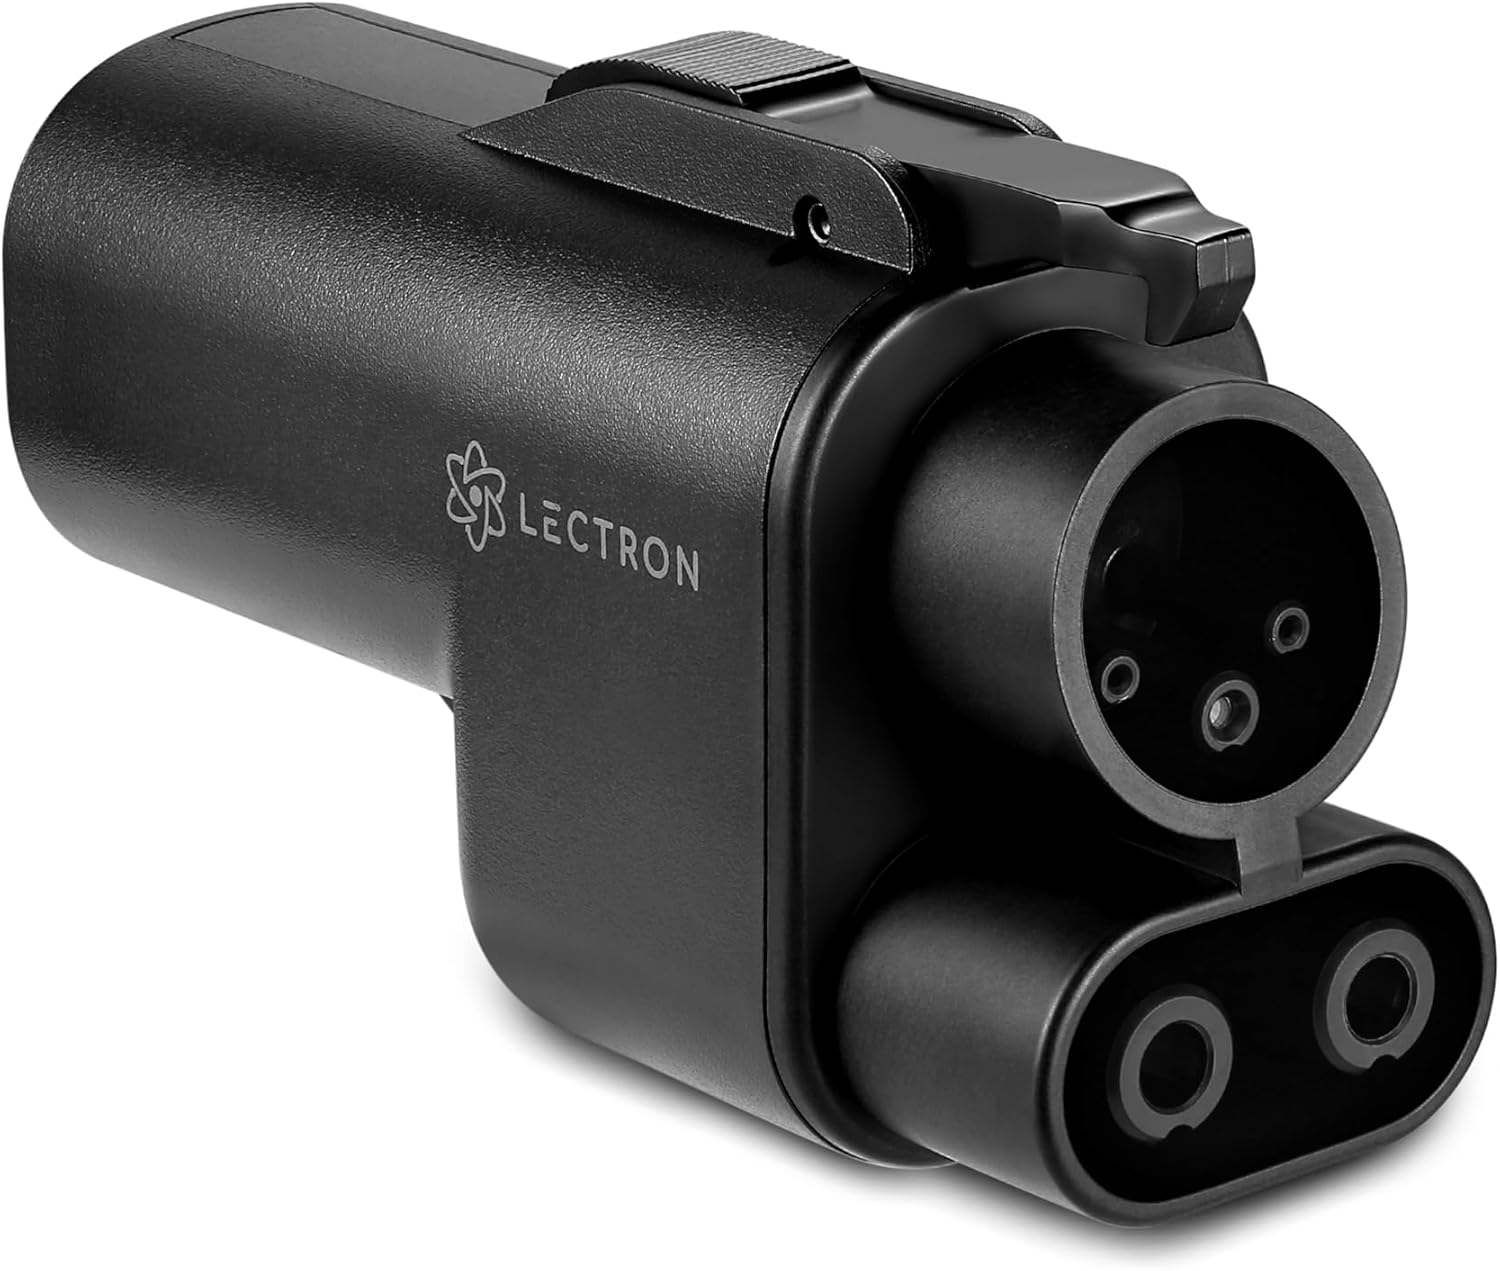
Lectron NACS to CCS Fast-Charge Adapter
Unlock every CCS fast charger for your Tesla, up to 500A DC. Never get stranded at a non-Tesla DC station again.
As an Amazon Associate, ThinkEV earns from qualifying purchases — at no extra cost to you.
Gear worth having
As an Amazon Associate, ThinkEV earns a small commission from qualifying purchases — at no extra cost to you.

Tesla Key Card Holder with AirTag Slot
Stop fishing the keycard out of your wallet, and slot an AirTag in case the car wanders off in a lot.
As an Amazon Associate, ThinkEV earns from qualifying purchases — at no extra cost to you.
October's Q3 Number Decides 2026
If auto margins hold flat ex-credits and Musk reaffirms a 2027 robotaxi date, the 300x multiple is defensible, barely, and only because the market is pricing the option, not the cars. If margins compress again or the autonomy guidance softens, there is nowhere for a forward multiple that rich to go but down. The Q3 print either buys Tesla another quarter of patience or it starts the repricing. Watch the auto margin line and the energy segment commentary. Everything else on the call is theatre around those two numbers.
Gear worth having
As an Amazon Associate, ThinkEV earns a small commission from qualifying purchases — at no extra cost to you.
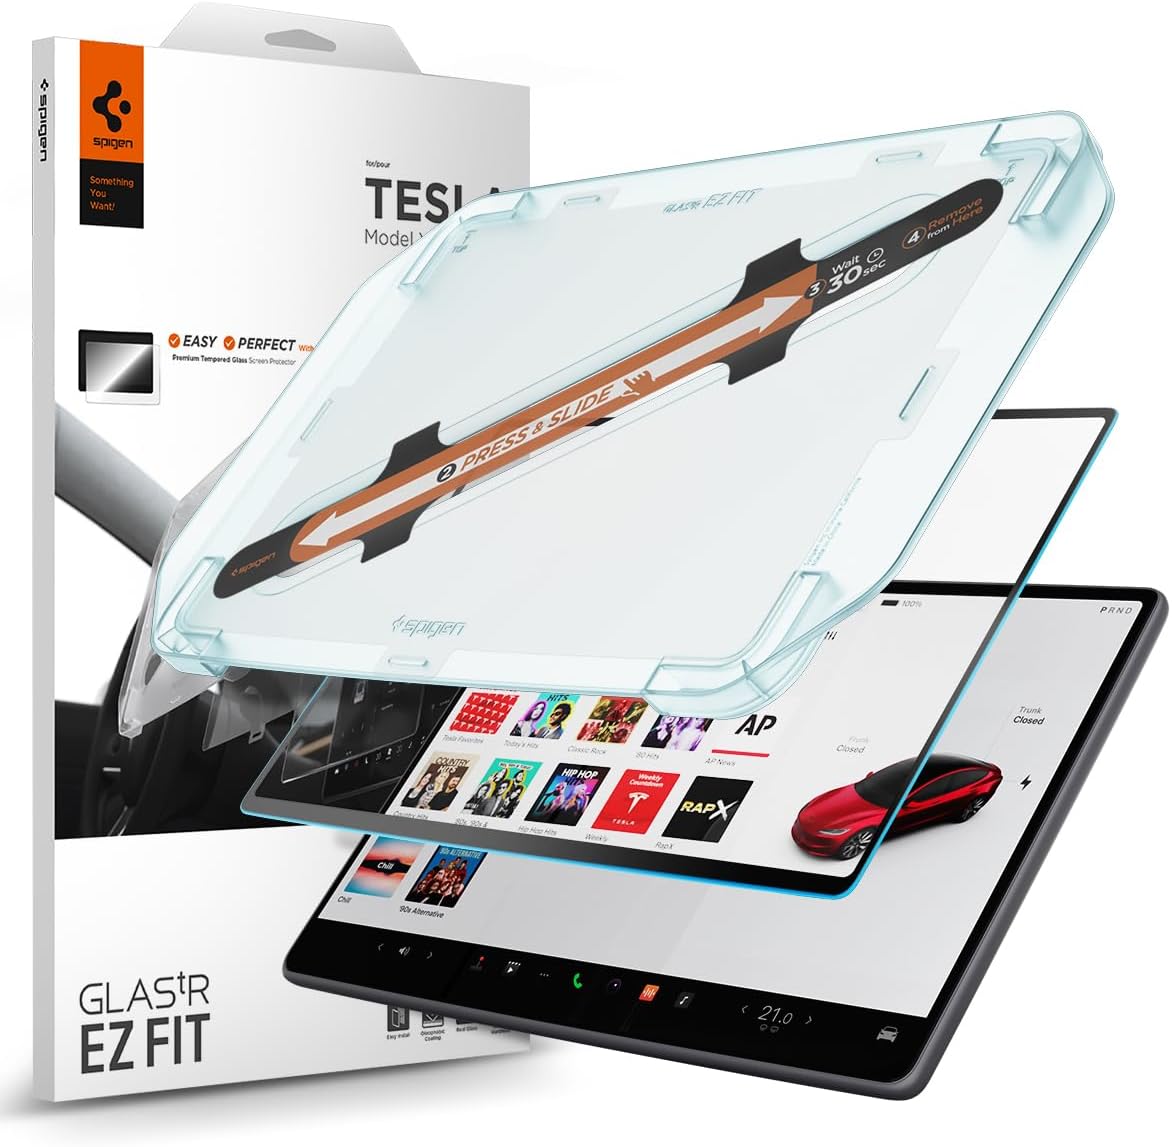
Spigen Tempered Glass for Tesla Model 3/Y
Tempered-glass protection for the touchscreen that kills fingerprints and scratches. Two minutes to install, lasts the life of the car.
As an Amazon Associate, ThinkEV earns from qualifying purchases — at no extra cost to you.
Founder & Chief Editor
Vlad Pereira is the founder and chief editor of ThinkEV.ca, the Canadian electric-vehicle publication he writes and edits from Courtenay, British Columbia. He covers EV pricing, federal and provincial rebates, charging costs, and the Chinese manufacturers now entering Canada, from the buyer's side rather than the press-fleet side. ThinkEV is a venture of Vlad Pereira Online; his writing on health, income and the long game lives at vladpereira.com.
Frequently asked questions
Why did deliveries beat estimates but revenue stayed flat?
What happened to Tesla's share of the Canadian EV market?
Is Tesla's energy storage business still a reliable growth driver?
Why does the stock trade at 300x earnings if profits are falling?
What's the single number Canadians should watch from the earnings call?
More EV & road-trip finds
Affordable upgrades worth a look — tap any to check the price on Amazon.
 ★ 1,340
Car Seat Gap Filler (Universal)
View on Amazon ★ 848
Coiled USB-C to USB-C Car Cable (2-Pack)
View on Amazon ★ 121
Foldable Windshield Sun Umbrella
View on Amazon ★ 17,839
Qifutan Vent Phone Mount (Military-Grade Clip)
View on Amazon ★ 9,349
Auto Detailing Brush Set (10-Piece)
View on Amazon ★ 537
USB Star Projector Roof Light
View on Amazon ★ 568
Personalized Photo and Text Keychain
View on Amazon ★ 4,424
Sun Visor Card and Document Organizer
View on AmazonRead, Plan, Then Stay Current
Explore our expert articles to understand incentives and ownership costs, use the map to pressure-test charging reality, then subscribe so new EV coverage comes straight to you.
Continue Reading
Tesla Pauses Model 3 Premium Orders in Canada, Blames the Quota. The Numbers Tell a Different Story
Used EVs Just Passed UK Safety Tests Better Than Petrol
California's $3,500 EV Rebate Leaves Tesla Out
Tesla Faces a Quebec Class Action Over Heat Pumps
Norway's -27C Winter EV Test: Chinese Cars Beat Tesla